Income Tax Rates and Bands
Understanding how income tax rates and bands work can make a big difference when planning your finances. In the UK, the system is designed to ensure fairness, with people paying taxes according to their earnings.
For the 2024-25 tax year, the income tax bands look like this:
Basic rate: 20% on taxable income up to £50,000.
Higher rate: 40% on taxable income between £50,001 and £150,000.
Additional rate: 45% on taxable income above £150,000.
Everyone gets a personal allowance, which is the amount you can earn tax-free. For 2024-25, the personal allowance is £12,570. But, here’s the catch: If you earn over £100,000, your personal allowance starts to shrink.
It’s a system that tries to make sure those who earn more pay a fairer share of tax. The more you know about how these bands work, the easier it is to manage your taxes and plan ahead!
Common Mistakes to Avoid When Filing Taxes
When we talk to clients at Pie Tax, we hear about the same mistakes over and over again, and trust us, they’re easy to fix!
One big issue is forgetting to claim deductions or credits. A lot of people miss things like business expenses or charitable donations that could lower their tax bill. We’ve had clients surprised to find out they were overpaying just because they didn’t know what to claim.
Another common slip up is filing late. Freelancers and self-employed people are especially prone to this, often forgetting to pay their estimated taxes throughout the year. The penalties add up fast!
We’ve also seen clients forget to report all their income, especially small amounts from side gigs or rental income. And remember, HMRC notices these things.
Finally, one of the simplest mistakes? Not double-checking your forms. Take your time, check everything, and if you’re unsure, let us help.
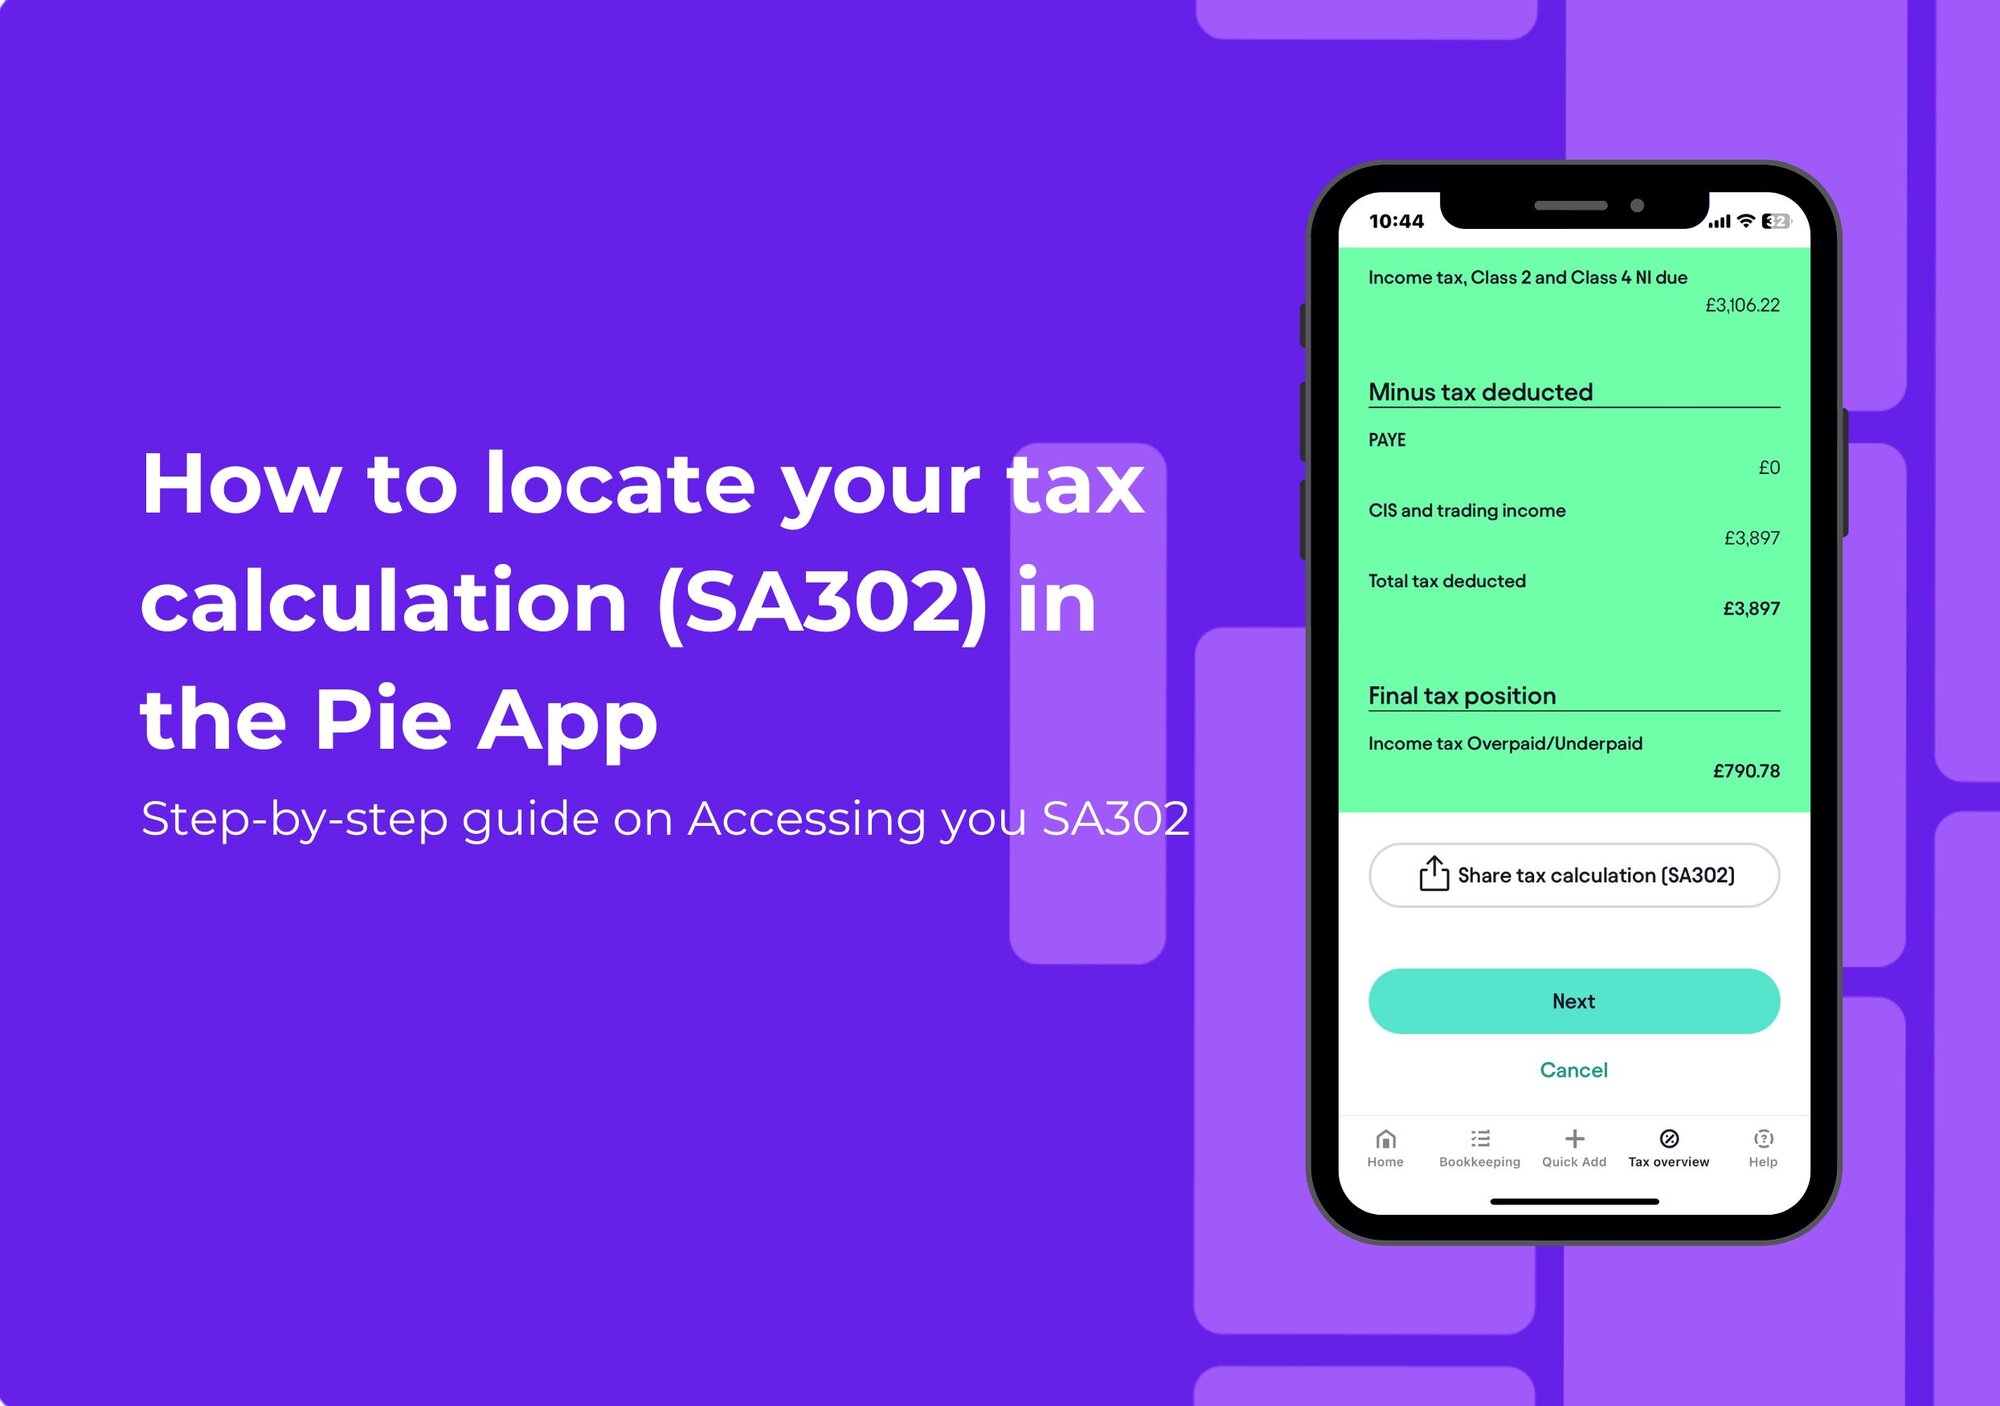
Talk to one of our advisors, or check out our free Pie Tax App. It’s what we’re here for!
How to Maximise Your Tax Refund: Tax Allowances and Reliefs
We’ve seen how a little effort can go a long way in getting you the refund you deserve.
Understanding income tax allowances is crucial. These allowances, such as the Personal Allowance, enable you to earn a certain amount before incurring any tax liability, significantly impacting your tax refund.
The first step? Claim all eligible deductions and credits. Many people miss out on things like work-from-home expenses, charitable donations, or tax credits for childcare. These can add up quickly and reduce the amount of tax you owe.
Another smart move is to use tax-saving accounts. In the UK, accounts like ISAs can help you earn interest or returns tax-free, while pension contributions can provide tax relief.
If you’re self-employed, tracking your expenses year-round is essential. We’ve had clients who didn’t realise they could claim for things like office supplies, travel costs, or even a portion of their utility bills.
Lastly, don’t underestimate the value of hiring a professional. A good tax adviser can spot savings you might not even know exist. It’s always worth having an expert double-check your return, you might be surprised at what you can save!
Remember, the more organised you are, the better your refund will be!