4. Understand Tax Brackets and Rates
The UK uses a progressive tax system with various income tax rates, meaning your income is taxed in portions based on specific bands.
The basic rate is 20% for taxable income up to £50,270, the higher rate is 40% for income over that up to £125,140, and the additional rate is 45% for anything above £125,140.
Here’s how it works: if your taxable income is £40,000, only the amount over £12,570 is taxed, and it’s all within the basic rate band.
If you earn £60,000, the first £50,270 is taxed at 20%, and the remaining amount (just £9,730) is taxed at 40%. Each portion of your income is taxed at the rate for its band, not your entire income at the highest rate.
We had a client who thought earning more meant all their income would jump into the higher rate. It doesn’t work like that, and understanding this saved them unnecessary stress!
5. Consider Deductions and Reliefs
Deductions and reliefs are your best friends when it comes to reducing your taxable income.
Expenses like business costs, charitable donations, or pension contributions can all lower the amount you pay tax on. It’s worth keeping track of these throughout the year to maximise your savings.
For example, if you’re self-employed, things like office supplies, travel expenses, or software subscriptions could all count as eligible deductions.
Even if you’re employed, contributions to your pension can provide tax relief, reducing the amount of income that’s taxed at different tax rates. Every little bit helps!
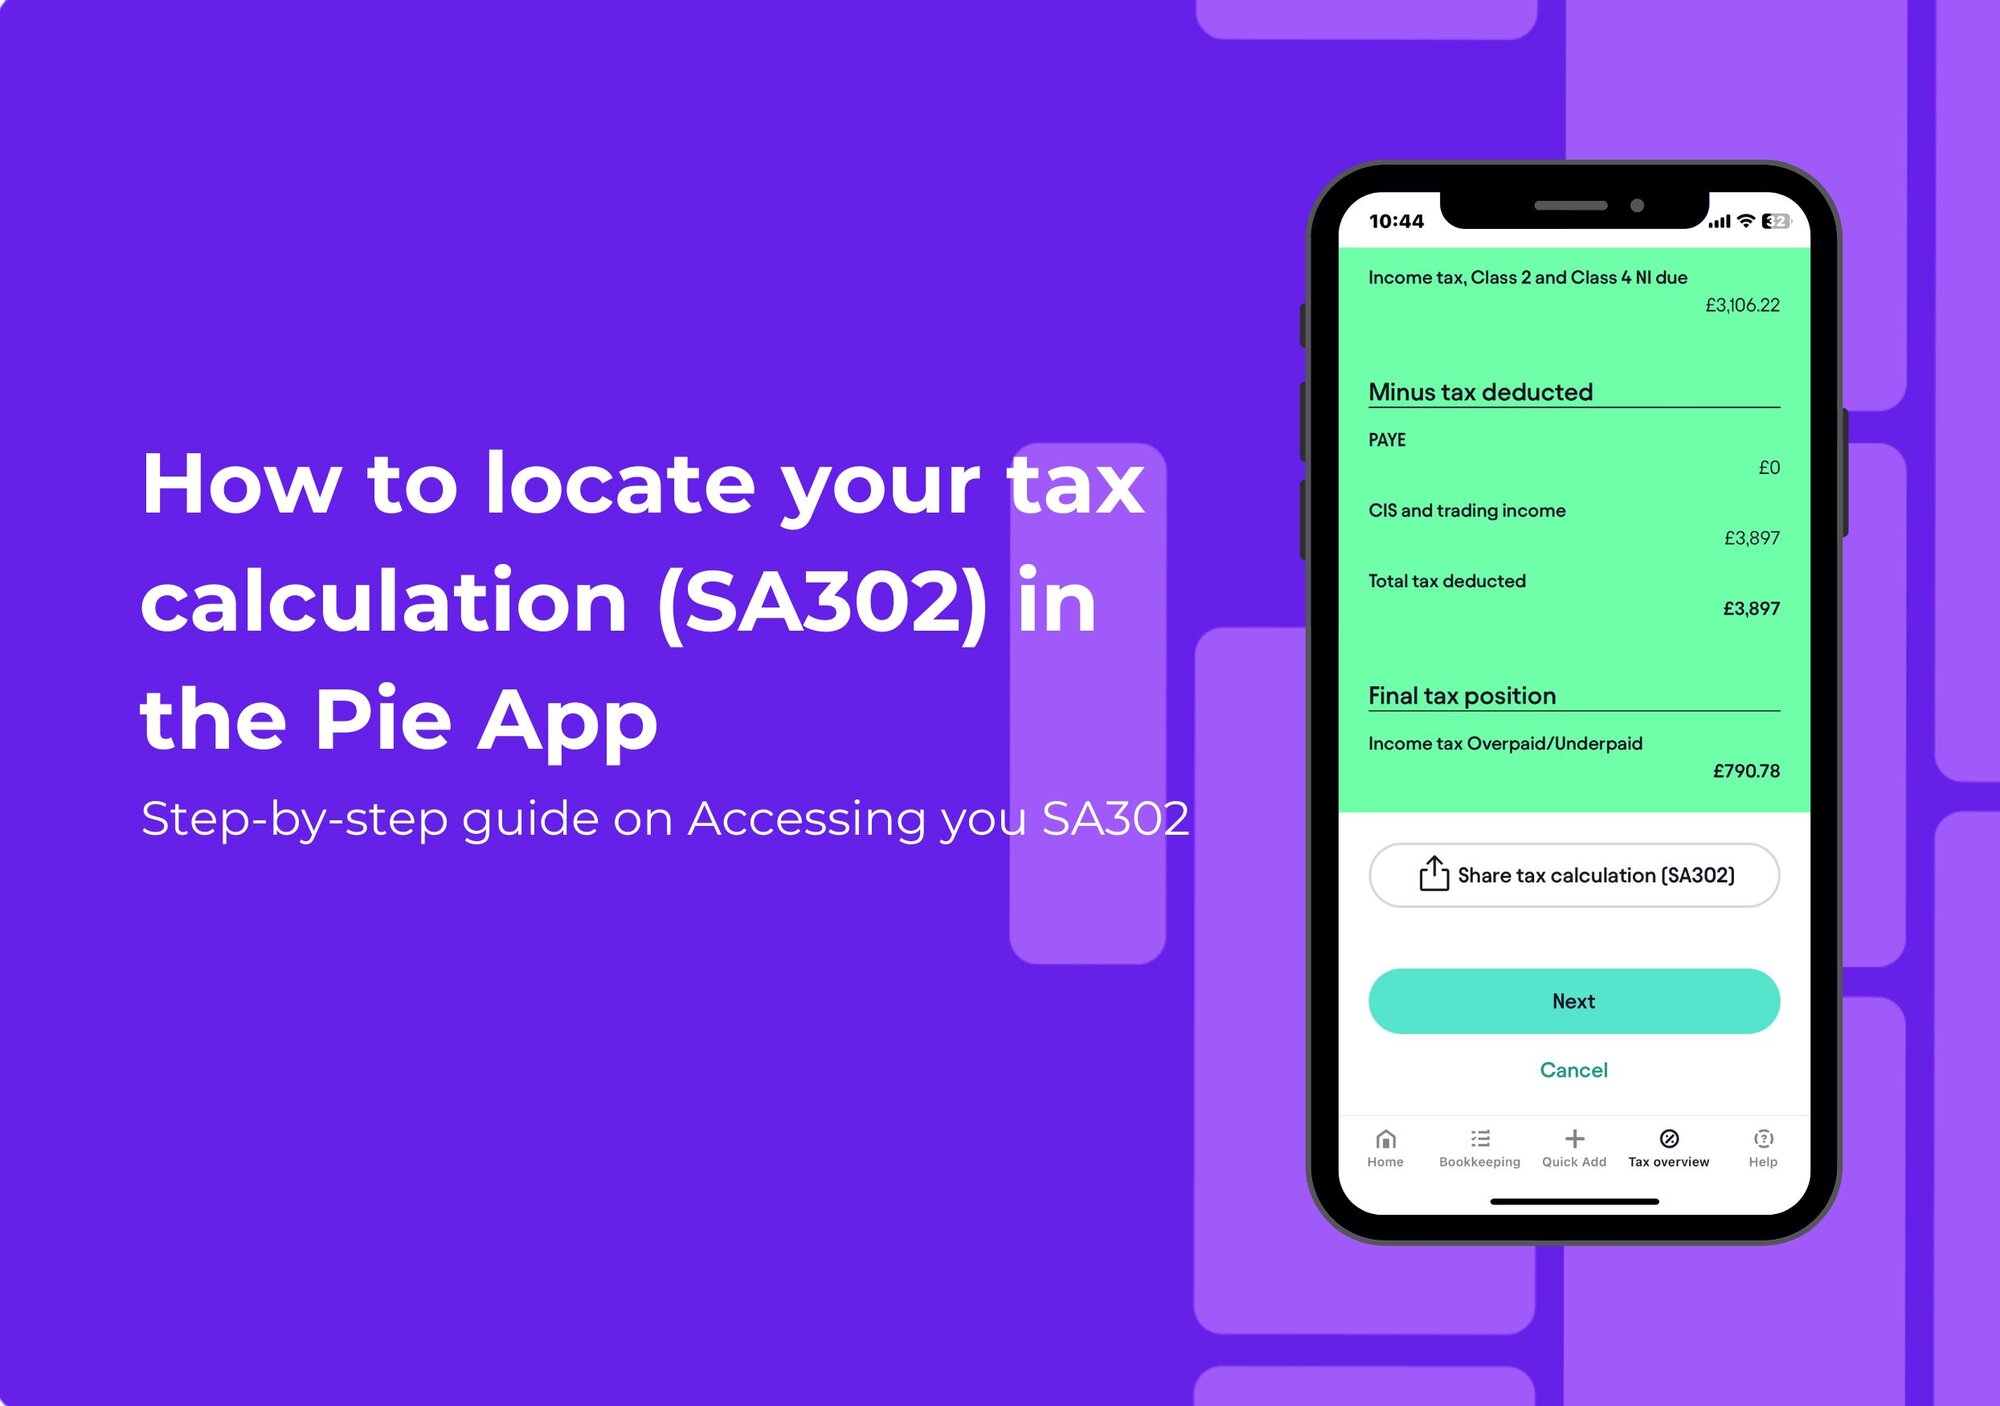
One of our clients discovered they could deduct home office expenses, which they hadn’t claimed for years. The Pie Tax app helps track and categorise deductions, so you don’t miss out on these opportunities to save!
6. Factor in National Insurance Contributions (NICs)
If you thought income tax was the end of it, don’t forget about National Insurance Contributions (NICs).
These are additional payments based on your earnings and employment status, and they help fund things like state pensions and healthcare.
Employees typically have Class 1 NICs deducted directly from their payslip, while the self-employed need to pay Class 2 and Class 4 NICs based on their profits.
For example, if you earn between £12,570 and £50,270, you’ll pay 12% NICs, and 2% on anything above that threshold.