How to qualify for EIS tax relief
Not every company or investor qualifies for EIS. The company must be UK-based, unquoted, and carrying out a qualifying trade. The company can’t have gross assets worth more than £15 million before your investment. After investment, this limit rises to £16 million. EIS eligibility and investment caps are also influenced by state aid regulations, which ensure compliance with government tax rules and prevent unfair competitive advantages.
It must have fewer than 250 full-time employees when the shares are issued. This helps target the scheme at genuine small and medium enterprisese As an investor, you can’t be “connected” to the company. This means you can’t be an employee, paid director, or hold more than 30% of the shares.
Claiming your EIS tax relief
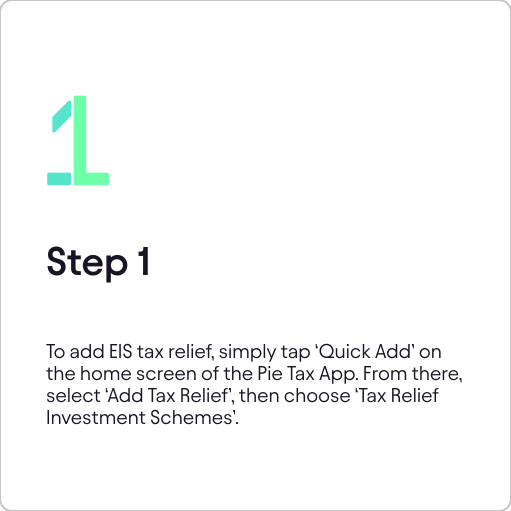
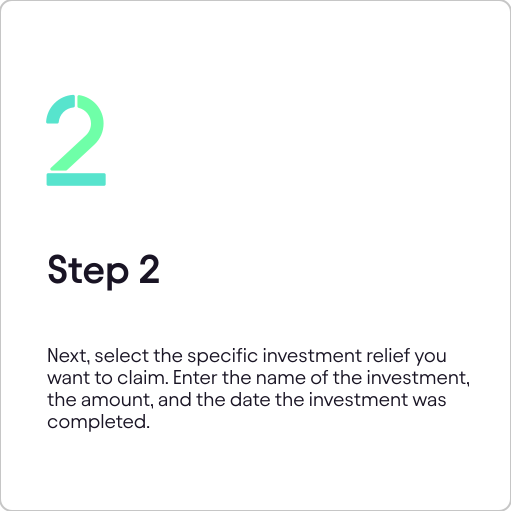
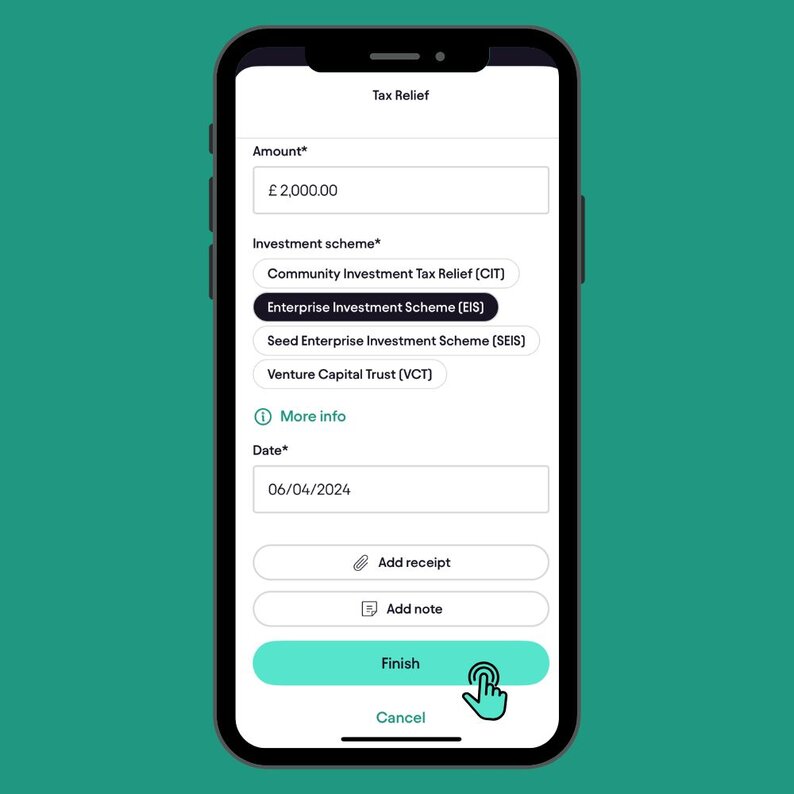
After you invest, the company will apply to HMRC for approval. Once approved, they'll send you an EIS3 certificate - your golden ticket to tax relief.
You claim the relief through your Self Assessment tax return. Simply enter the details from your EIS3 certificate in the appropriate section.
You can even carry back EIS relief to the previous tax year. This flexibility is particularly useful for tax planning purposes.
Most people receive their relief either as a tax rebate or as a reduction in their tax bill. I once received a £4,500 rebate from a £15,000 EIS investment – a welcome boost to my finances that year!
Watch out for these EIS pitfalls
Remember that three-year holding period? If you sell your shares earlier, HMRC will claw back your tax relief. The company needs to keep following EIS rules during those three years too. If they break the rules, your relief could be withdrawn.
Certain “excluded activities” don’t qualify for EIS. These include property development, financial activities, and energy generation. Some investors get caught out by the “connected persons” rules. Check you’re not too closely linked to the company before investing.
Other schemes, such as social investment tax relief, have their own eligibility criteria and pitfalls, so investors should review the specific rules before investing.
EIS vs SEIS: What's the difference?
The Seed Enterprise Investment Scheme (SEIS) is EIS’s little sibling. It’s designed for very early-stage companies just starting out. EIS and SEIS are both venture capital schemes created to support smaller businesses, and there are other venture capital schemes available for different types of companies.
SEIS offers even more generous tax relief - 50% rather than 30%. However, investment limits are much lower at £100,000 per tax year. Companies can raise a maximum of £150,000 under SEIS. This compares to the £5 million limit under EIS.
Many startups use SEIS for their first funding round. They then move to EIS as they grow and need more capital.